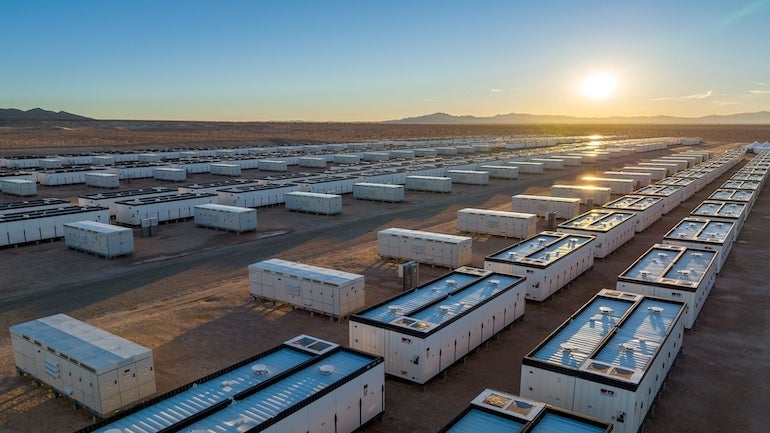
Battery energy storage system (BESS) sites report a median 96.7% availability, but measured by whether components respond when called, it is 94.1%. Research by ACCURE Battery Intelligence in a new report published on 21 September sets out how gaps of that kind affect coverage ratios and returns.
Across 50+ operating BESS projects, most sites over-report availability, deliver less dispatchable energy than their capacity tests imply, and age more slowly than warranty curves assume, though aging is not what erodes the overbuild.
The report includes financing lessons for lenders and investors, gleaned from from over 50 operating battery projects. The report from ACCURE, compiled with support from US Bank, covers 4 GW of installed power capacity and 10 GWh of energy capacity across key markets including ERCOT and CAISO in the United States, the UK and Germany. It tests the availability guarantees, capacity tests and warranty degradation curves on which BESS financial models are built.
Owners build in headroom to absorb losses and degradation. The median project carries a DC overbuild of 20.2% above nameplate energy; conversion losses take 7.6 percentage points, usable capacity losses 5.2, and the operational performance gap 6.9. This means the median site enters commercial operation with 0.5% operating headroom above nameplate, and some start below it. None of that is caused by aging.
Reported availability
The median Reported Site Availability is 96.7%, in line with the conventional 97% target. But those values come from reporting formulae that vary from contract to contract, and often count a component as available whenever it reports an ‘online’ status rather than when it responds. Counting a component as available only when it participates as the energy management system calls on it, the median falls to 94.1%. The gap averages 2.6 percentage points, three out of four sites over-report, and at the tenth percentile it reaches 6 percentage points. Contractual Availability, which excludes downtime caused by Excuse Events, is higher again.
These deviations in what the assets actually deliver, not just how formulae count them, cost money. Applied to a representative BESS project and financing model, a 2% reduction in revenue moves a loan sized at 1.30x debt service coverage ratio to roughly 1.26x, and takes about a point off the sponsor’s levered internal rate of return.
The power conversion system is the largest single source of unavailability at 36.4%, ahead of balance of system, racks and containers. Most of that downtime comes from small, recurring outages that early detection and predictive maintenance can catch.
Moreover, in live operation, the median site delivers 6.9% less dispatchable energy than its capacity test implies, driven by unavailability and stranded energy from cell imbalance. This is the ‘operational performance gap’, not a further loss. Errors in state of charge estimation sit outside that figure and carry their own cost, which can reach $1 million or more per GWh of installed capacity a year.
Slower aging does not create spare headroom
State of health runs 1.8 percentage points above the average warranty curve in the early years, and degradation averages 1.6% a year against the 1.7% warranted. But a warranty curve is a commercial decision, not necessarily an accurate picture of how the battery ages, and because the supplier pays when an asset falls short, the curve carries a buffer. And with 0.5% operating headroom at the start, it is conversion, usable capacity and operational performance losses, not degradation, that consume the overbuild first. An asset aging more slowly than modelled while running below potential is underused, not ahead.
Darya Rüwald, director of Battery Intelligence at ACCURE and co-author of the report, said: “Lenders and investors rely on contracts, warranties and capacity tests to build their models. Those documents flatter the asset on availability and capacity, and carry commercial buffers on aging. The median site enters its first year with half a percent of margin above nameplate. That is where every financing case should start. None of this is a reason to avoid BESS investments; the asset class is maturing fast and the grid needs more of it. But trust is easier to extend when the baseline is measured performance rather than contractual assumption. That is what we have put on the table.”
Kai-Philipp Kairies, CEO and co-founder of ACCURE, added: “Every maturing asset class reaches the point where measured field performance, not the contract, sets the baseline for financing. Solar and wind made that transition; storage is arriving there now and can get there faster.”
The full report is available at https://www.accure.net/ebooks/banking-bess


